When could work become optional?
Enter a few figures to get an estimated date. Nothing you enter here is sent anywhere.
Time to financial independence
18 years 4 months
That is February 2045, the year you turn 48.
A deliberately simple estimate: one steady return, in today's money, before tax. The full app tests the plan across 10,000 simulated scenarios. Treat any date as an estimate, not a promise.
Work out your own date
Your numbers
Assuming a 7.0% return before inflation, 3.0% inflation and a 4.0% withdrawal rate.
What you track
You record what you own and what you owe, and update the balances when you like. No bank connections, and nobody else holding a copy of your accounts.


- Assets and liabilities
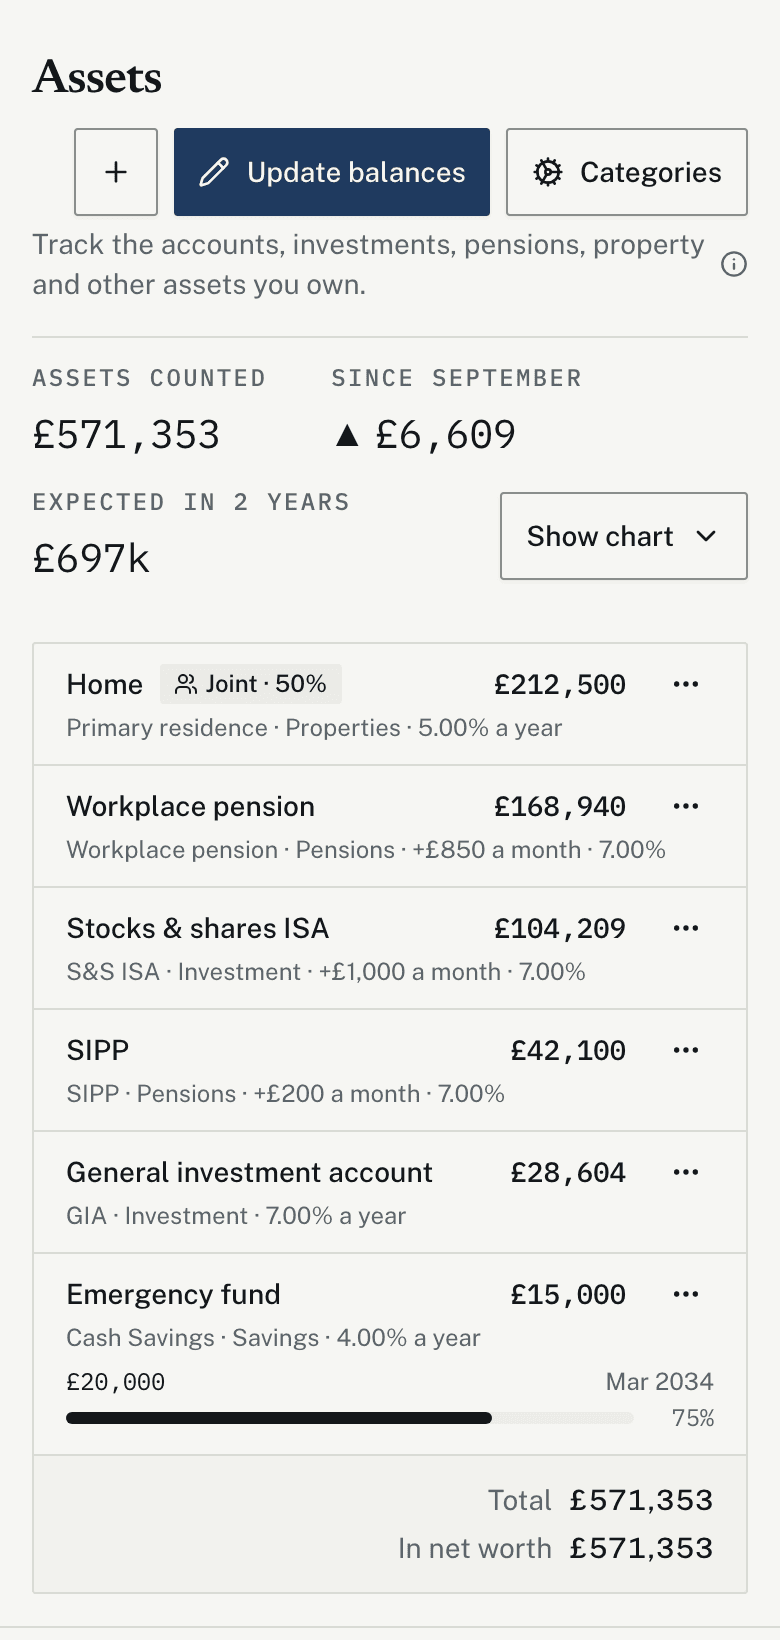
- Each with its balance and monthly payment. Investments grow at the rate set for their kind; a savings account keeps its own.
- Balance updates
- A whole month in one pass. A skipped month carries the last figure forward.
- Exclusions
- Keep the home you live in out of the maths without deleting it.
- Scenarios
- Add a lump sum or a career break and see the date move.
- Goals
- Put a target on an account, like a child's ISA or a rainy-day fund, and see when you get there.
- Display currency
- One currency of your choosing, on every screen.
Two people, one horizon
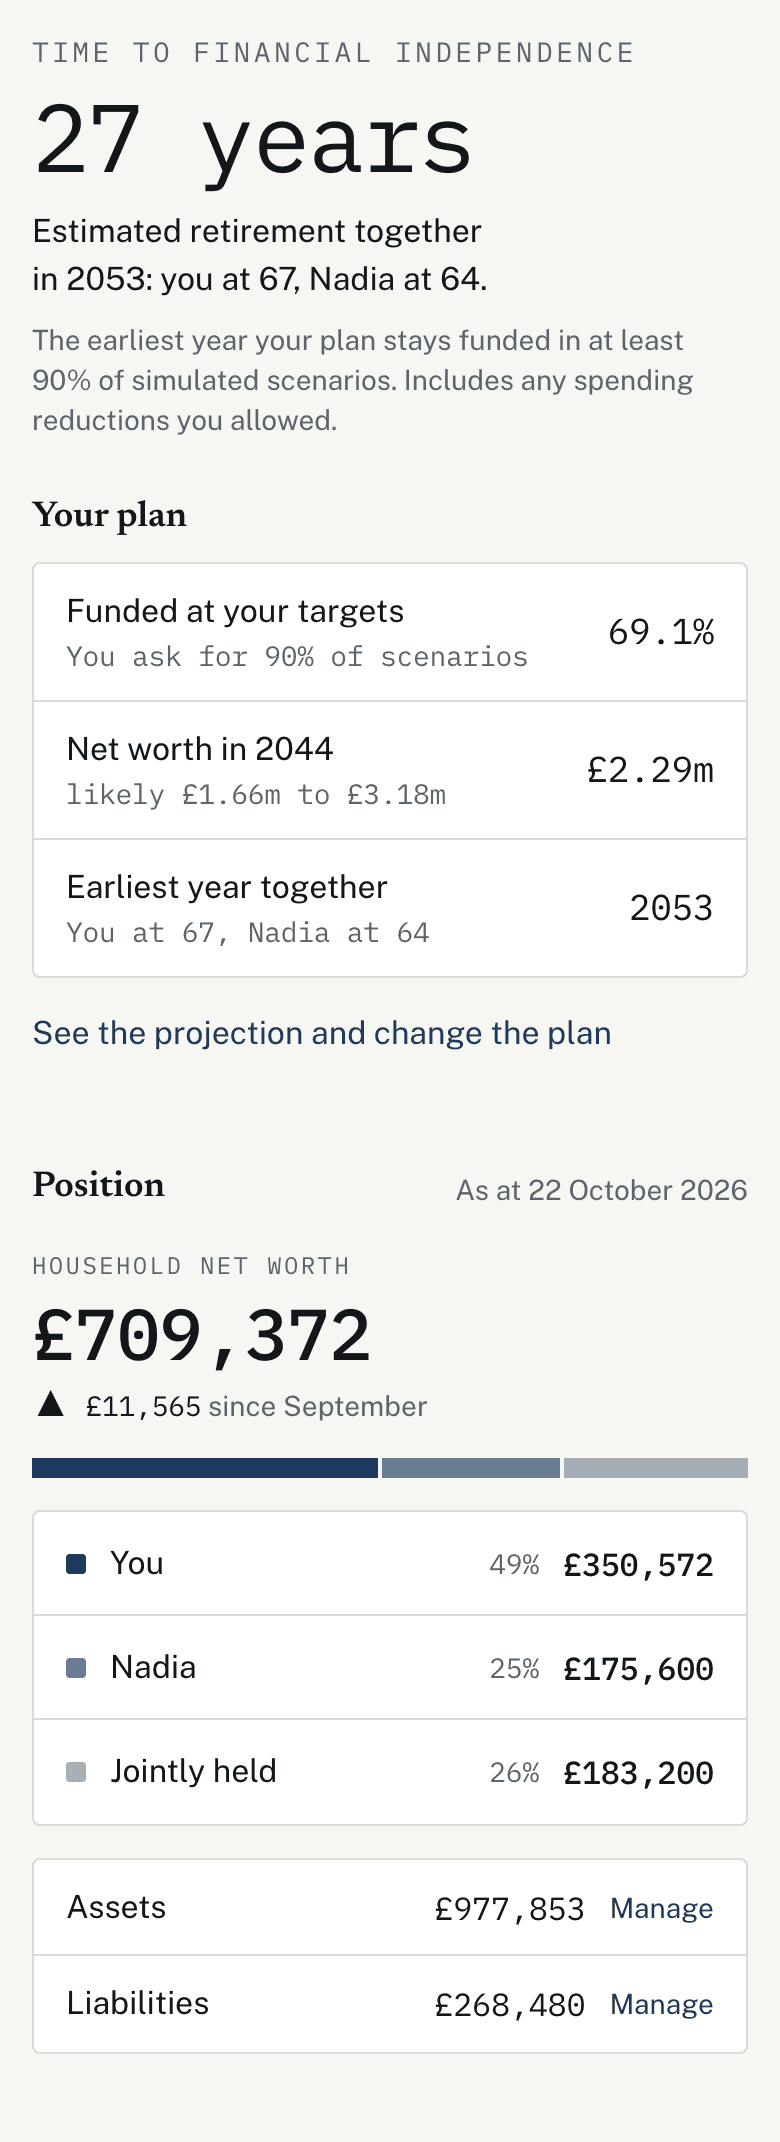
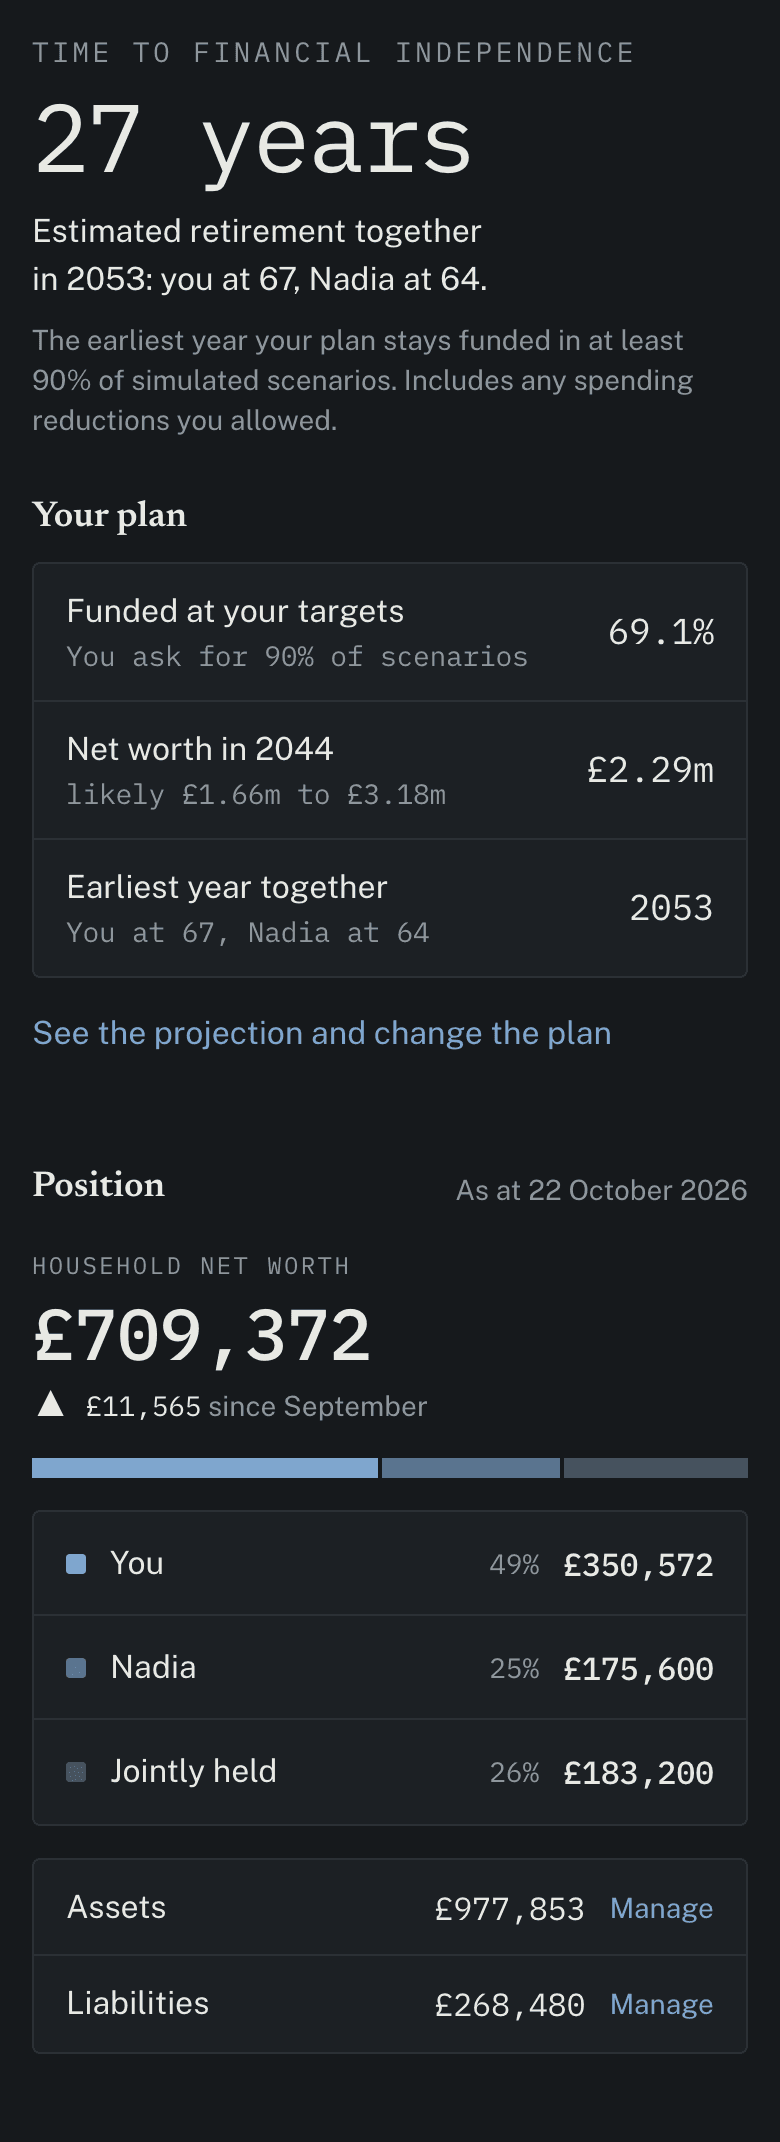
Most trackers assume one person. Link a partner and you each keep your own column, beside the household's, against one target and one date.


- A column each
- Yours, theirs, what you hold jointly, and the household's total.
- A date each
- The household's year, and the year each of you would reach alone.
- One switch
- Flip between your view and the household's. Who owns what stays put.
How it works
Four steps, and the fourth is the only one you repeat.
- 01
Open it in your browser
No account. Your figures stay in your browser.
- 02
Record what you own and owe
Each account once, with its balance and what you pay in.
- 03
Set the income you need
That and a withdrawal rate make your target.
- 04
Update when you like
Monthly is plenty. Each update moves the date.
What the projection assumes
A date is only as honest as the assumptions under it. These are the main ones. The app shows them all and lets you change almost every one.


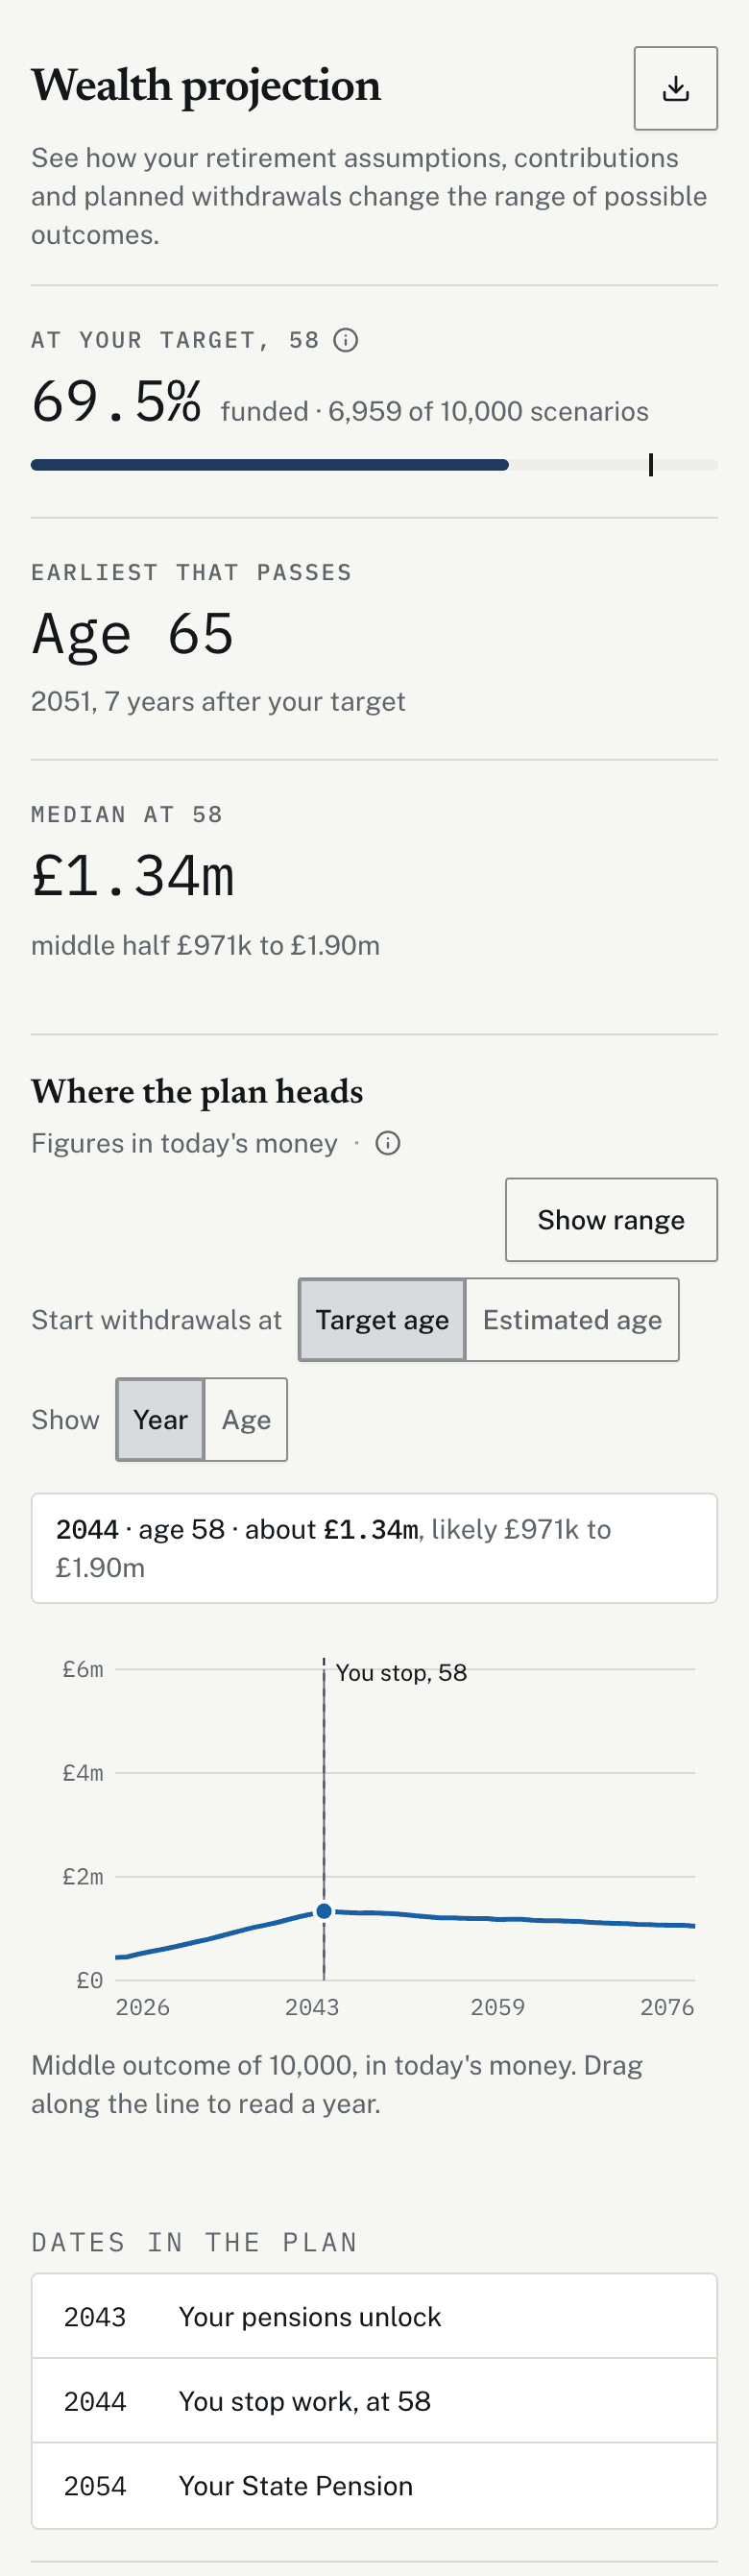
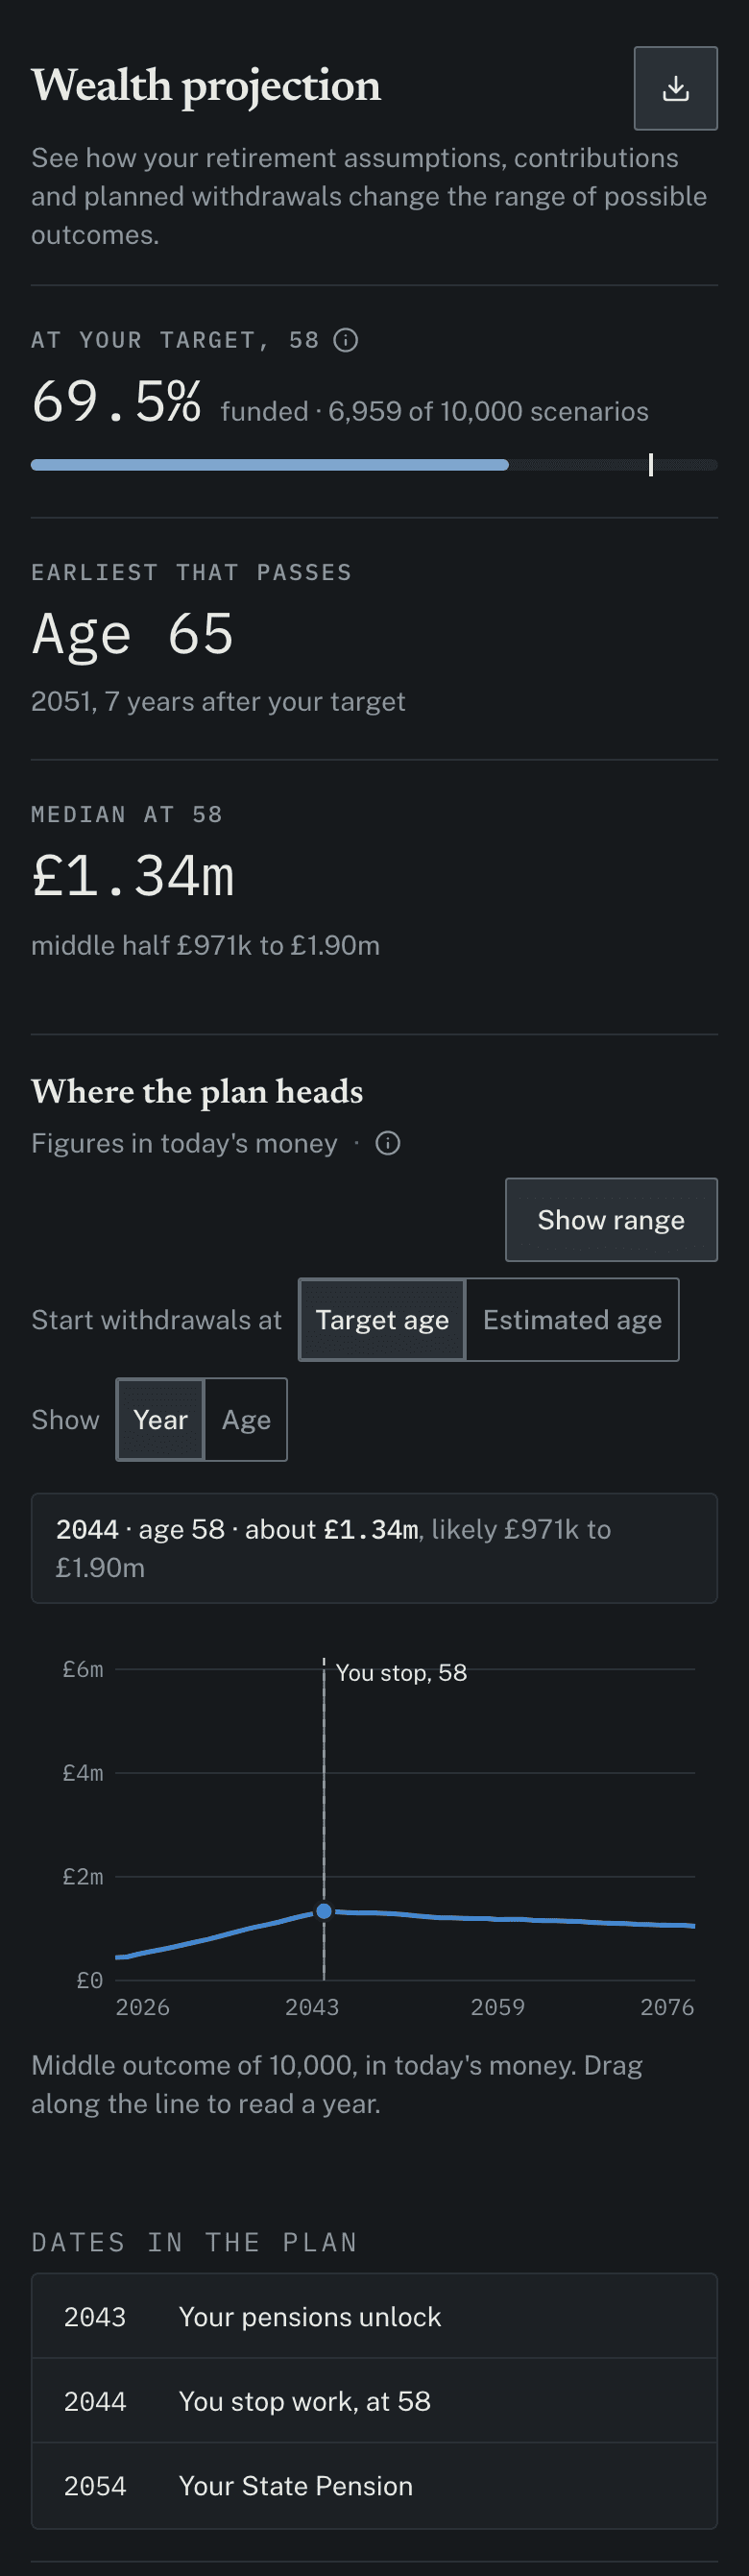
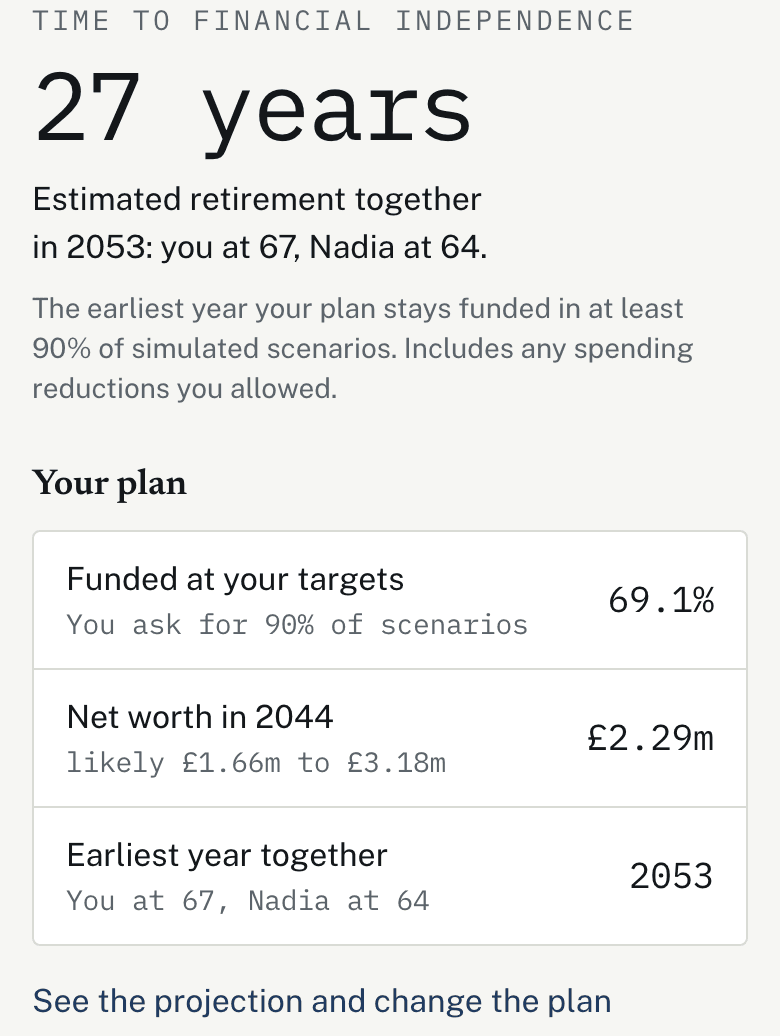
The sample plan wants to stop at 58. It is funded in about seven of every ten futures and asks for nine in ten, so the estimate is 65.
- 10,000 simulated scenarios
- A range of outcomes, not one line drawn at the average.
- Today's money
- Every future figure is shown with inflation taken out.
- Before tax
- Personal tax is not calculated, so use before-tax figures.
The full methodSix definitions, from the FI target to what the model leaves out
- Financial independence target (FI target)
- Your annual retirement-income target divided by your withdrawal-rate benchmark. At the default 4%, that is twenty-five times your annual income. It is a comparison point, not a guarantee that the portfolio will fund retirement.
- 10,000 simulated scenarios
- The projection shows a range of outcomes and the share of scenarios in which the plan funded your retirement income. This is more realistic than a single line that assumes markets return exactly their average every year.
- Drawn from the record
- Each scenario uses sequences based on historical UK inflation and market data. Returns still centre on the assumptions you choose; the historical data creates realistic variation around them.
- Today's money
- All projections are shown in today's money, so a future £40,000 is shown with roughly the purchasing power £40,000 has today. The model varies inflation between simulated years rather than assuming prices rise by exactly the same amount every year.
- Growth
- Annual, so £100 at 7% becomes £107 rather than £107.23. Investments grow at the rate you set for their kind, such as shares or property; a savings account or a fixed-rate bond grows at its own. Contributions are spread through the year rather than landing on the first of it. A mortgage amortises at its own rate and is netted off once inflation has been taken out of it.
- What the model does not include
- The model does not calculate personal tax or the different tax treatment of pensions, ISAs and taxable investments. It does not rebalance your portfolio, so holdings can drift as some grow faster than others. Pension access ages are respected where the product has enough information to apply them.
See where you would stand
The whole product, in your browser. No account, nothing to cancel, and your figures never leave it.